Author name: WebDev

Film crew checking camera gear for production staffing compliance.
Production Staffing Compliance

Production Staffing Compliance for Short-Term Crews

Production staffing compliance can slip through the cracks when a shoot lasts only a few days. A producer may book a camera operator on Monday, add an assistant on Tuesday, and wrap by Friday. A simple plan can help you track who is working, how they will be paid, and which records need to be kept. Why Production Staffing Compliance Starts Early A short job still needs a clear hiring process. Before the first call time, decide who will handle crew records, time sheets, and pay questions. Put one person in charge of sharing changes with the payroll team. That way, a new crew member or a late schedule change does not get lost in a chain of messages. Start with a crew list. Include each person’s role, start date, work site, pay terms, and the person who approves their hours. Check the list against the shoot plan each day. If someone joins for a pickup day or moves to a new location, update the record while the details are fresh. Check Crew Status Before the First Shift Calling someone a freelancer does not settle how they should be treated for pay and tax purposes. The working relationship matters, including how the job is directed and carried out. A one-day booking is still worth reviewing. Speak with your payroll or HR team about each role before you set up payment, especially when a worker has been booked in different ways on past shoots. Give each crew member clear terms in writing. State the role, rate, expected dates, and where to send time records. Explain who can approve extra hours and what happens if the shoot runs late. Clear terms give everyone a shared point of reference. Keep Production Staffing Compliance on Set The first day can be hectic. Gear arrives, call times shift, and a missing form may feel less urgent than a missing light. Still, onboarding needs space in the schedule. Collect the needed hiring and payroll details through a secure process. Confirm who is responsible for each step before the crew starts work. Use a short checklist for every new arrival: A repeatable process helps when several people join on different days. For more support with this step, see the employee onboarding service. Track Each Workday, Not Just the Shoot Date A call sheet shows the plan, but a time record shows what happened. Keep actual start and end times, breaks, and any extra hours in one place. Ask a lead to review time each day, while crew members can still flag mistakes. If a call time changes, record the new time instead of relying on the first schedule. Daily records also make it easier to handle split locations or last-minute pickup shots. Keep approved rate changes with the same project records. When the shoot ends, match the time sheets to the crew list before payroll closes. This gives you a chance to spot missing names, duplicate entries, or hours that need another look. Federal rules require covered employers to keep certain wage and hour records; state rules may add more. Make Payroll Part of the Shoot Plan Set a deadline for time sheets before the first day. Share it with crew leads, then choose who will send approved hours and changes to payroll. Do the same for travel, gear fees, and other agreed costs, so they do not end up in a separate message after the project closes. Record each item clearly and ask your payroll team how it should be handled. A busy final day is a poor time to settle an unclear rate or missing workday. If one person works on more than one project, make sure the records show where their time belongs. Learn how the payroll services page covers wage processing and payroll records. FAQ: Short-Term Crew Staffing Does a short shoot need onboarding? Yes. A brief job still calls for clear pay details, work rules, and the forms that apply to the worker. Start the process before the first shift so there is time to fix gaps. Can a call sheet replace a time sheet? No. A call sheet records planned work. Keep a separate record of the hours actually worked, including changes made during the day. Who should approve crew hours? Choose a production lead who can confirm the work. Tell crew members how to report a mistake before approved hours go to payroll. What should happen after wrap? Check final hours, rates, and outstanding expenses. Keep the records together so your team can answer pay questions later and prepare for the next shoot. Close the Shoot With Clean Records Good production staffing compliance comes from small checks at the right time. Review crew status before hiring, collect details as people arrive, and confirm hours before payroll runs. When each step has an owner, your team can focus on the work on set and still close the project with a clear record of who worked and what they are owed. Ready to plan your next crew? Incorp Technical Resources, LLC supports media teams with onboarding and payroll for short-term projects. Contact us to discuss your crew, and visit our blog for more workforce tips.
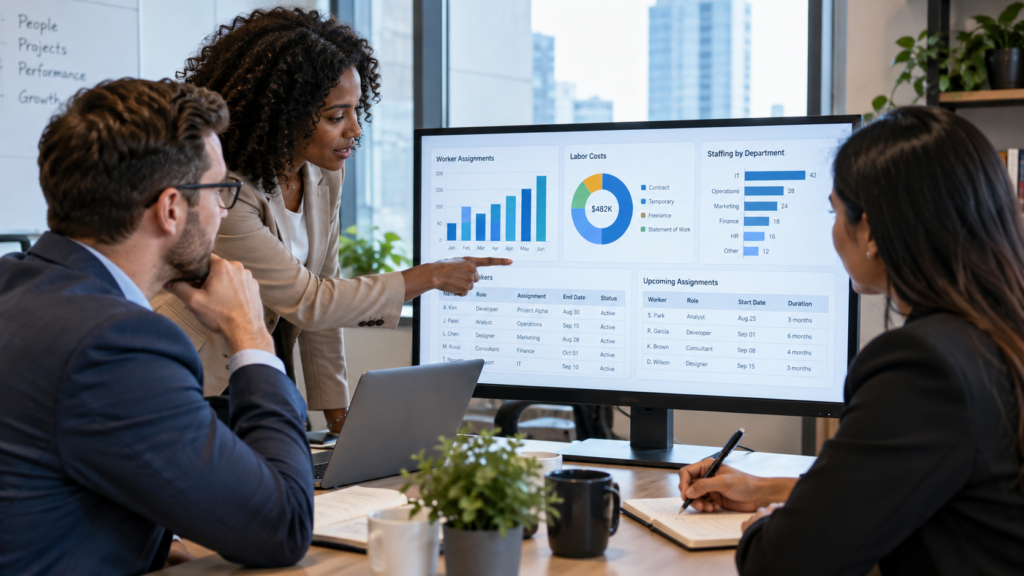
Contingent workforce management team reviewing worker assignments, labor costs, and staffing details on a computer.
Contingent Workforce Management

Contingent Workforce Management and Cost Visibility

Contingent workforce management helps businesses track temporary workers, contractors, labor costs, and project needs in one clear process. Without a set system, worker details can become spread across emails, files, and separate reports. This can make it harder to know who is working, what they cost, and where they are assigned. A clear process helps teams keep better records. It can also make it easier to plan budgets, check labor costs, and manage workers from one project to the next. Why Contingent Workforce Management Matters A contingent workforce may include contractors, freelancers, temporary workers, and short-term staff. These workers can help a business handle busy seasons, special jobs, and changing work needs. Problems can start when each team tracks workers in a different way. One manager may use a spreadsheet. Another may use email. Payroll may have a separate record. This can make labor costs hard to follow. Contingent workforce management helps bring key worker details into one process. Businesses can track: When these details are easy to find, managers can see where labor money is going. Contingent Workforce Management Tracks Costs Knowing a worker’s hourly rate is only one part of labor cost. A business may also need to track overtime, taxes, payroll fees, insurance, and other costs tied to the job. Clear records help managers compare planned costs with real spending. This can show when a project is using more labor than expected. It can also help teams spot cost changes early. Good worker records also support payroll services. Clear hours, pay details, and assignment records can make payroll easier to review. They also help teams see how much labor is being used on each job. See Worker Status and Job Details Cost tracking works better when worker status is clear. Managers should know if a worker is active, ending a job, waiting for approval, or moving to a new project. This helps HR, payroll, and project teams stay on the same page. A clear worker record may include: These simple details can prevent confusion. They can also reduce the need to search through many files or emails. Contingent Workforce Management Helps Planning Clear labor data can also help with future plans. Past records can show how long workers stayed on a project, how much labor cost, and when more staff were needed. Managers can use this information when planning new work. For example, a past project may have needed more hours than first planned. That information can help build a better budget next time. A team may also see that some jobs only need extra workers for a short time. This can help managers plan staff levels with more care. Simple reports can show: This information can also support other HR services. Payroll, worker records, onboarding, and job tracking often work better when teams use the same clear process. Keep Teams on the Same Page HR, payroll, accounting, and project managers may all need worker data. If each team uses a different record, mistakes can happen. Hours may not match. Job dates may be wrong. Labor costs may be placed under the wrong project. A shared process helps reduce these gaps. For example, a project manager may approve hours. Payroll may process pay. Accounting may track costs for the job. If each team sees the same worker details, it is easier to check the numbers and fix errors. Regular reviews can also help. Teams can check active workers, end dates, missing approvals, and cost changes before small issues grow. FAQ About Contingent Workforce Management What does contingent workforce management track? It can track workers, jobs, hours, rates, costs, dates, and worker status. The exact setup may change based on the needs of the business. How does it help track labor costs? It gives managers a clearer view of worker hours, rates, and project costs. This makes it easier to compare a budget with real spending. Can it help with payroll? Yes. Clear worker records and approved hours can help payroll teams work with more complete information. Can it help with staffing plans? Yes. Past worker data can help managers plan future labor needs, set budgets, and decide when extra staff may be needed. Get a Clear View of Workforce Costs Temporary workers and contractors can help a business stay flexible. They can also create more records, labor costs, and job details to manage. Contingent workforce management gives teams a clearer way to track workers, costs, and job status. It can also help managers plan future staffing and keep labor spending easier to understand. For help with payroll and workforce support, Incorp Technical Resources, LLC provides services that can make worker records and labor tasks easier to manage. Contact us to discuss your workforce needs. For more helpful articles, visit the Incorp Technical Resources, LLC blog.

An employee smiles at his computer while holding a stack of money.
Payroll Systems

The Evolution of Payroll Systems: From Manual Books to Cloud Solutions

The Evolution of Payroll Systems: From Manual Books to Cloud Solutions Home Blog Before software and servers, payroll was managed using handwritten ledgers, wall calendars, and metal timecards. Clerks tallied hours with pencil and ruler, calculated wages with rate tables, and walked envelopes of cash to pay lines. Accuracy depended on the steadiness of a bookkeeper’s hand and the clarity of the foreman’s notes. Minor errors—an illegible 7, a smudged overtime mark—could cascade into disputes, morale problems, and compliance headaches. Early payroll systems were primarily focused on arithmetic and trust, and the workload increased as headcounts expanded. These humble beginnings set the baseline problem that modern payroll systems still solve: transforming messy, human inputs into precise, timely pay—every time. Why Industrialization Pressured Payroll Systems To Standardize As factories scaled and shifts expanded, manual methods began to buckle. Weekly headcounts soared, job classifications multiplied, and differential rates for night work, hazardous duty, or premium skills turned simple math into a maze. Labor laws emerged to curb abuses and formalize the regulation of overtime, minimum wage, and record-keeping. Companies needed repeatable, defensible processes. Standard forms, fixed pay periods, and consistent deduction rules became essential. During this period, payroll systems transitioned from ad hoc practices to documented workflows—an early indication that process discipline, not just calculation speed, would ultimately determine success. The Punch Clock Era and What It Taught Payroll Systems Mechanical time clocks stamped start and stop times with unblinking regularity. They reduced arguments about attendance, but introduced their own friction: lost cards, buddy punching, and reconciliation drudgery every pay period. Payroll teams learned that better inputs reduce downstream pain—the foundational insight behind every modern integration and timekeeping upgrade. Mechanical Timekeeping Limits Stamps capture presence, not productivity or location. Context still had to be reconstructed after the fact. Compliance Before Computers Auditors requested paper trails, and clerks created them by filing punch cards and ledgers in warehouse-like archives. Data Bottlenecks Even reliable stamps created mountains of data that humans had to summarize, check, and key in by hand. Mainframes Brought Batch Processing To Payroll Systems When mainframes arrived, large employers adopted batch processing that ran overnight to process timesheets, rates, and deduction tables. The big win was consistency: once the rules lived in code, outputs became repeatable and auditable. Companies could handle union contracts with layered premiums, tax withholding changes, and benefit deductions at scale. But power came with rigidity. Change requests required queueing with IT, testing on development machines, and waiting for the next payroll cycle. Payroll systems became fast and centralized, yet they were heavy, expensive, and slow to adapt—proof that speed without agility would never be enough. PC Software Payroll Systems for Small Businesses The rise of desktop software finally gave smaller employers control. Affordable programs offered prebuilt tax tables, W-2 generation, and simple reporting. Office managers could process pay in-house instead of mailing hours to a service bureau. The tradeoff was operational responsibility: updates had to be installed, backups scheduled, and compliance monitored. Templates Replaced Math Errors Common pay scenarios can be saved as templates, reducing the need for repetitive data entry and minimizing arithmetic errors. Local Backups Had Risk A failed hard drive or stolen laptop could jeopardize years of payroll history if safeguards were lax. One Desk, One Knowledge Base Know-how concentrated with a single person, creating business continuity risk during turnover or illness. Regulation Continually Shaped Payroll Systems in the Late Twentieth Century Tax codes evolved, benefits diversified, and reporting obligations multiplied. Cafeteria plans, retirement contributions, garnishments, and jurisdictional taxes turned payroll into a compliance engine as much as a payment pipeline. Each new rule demanded updates to tables, forms, and workflows. Vendors rushed to publish patches and knowledge bases, while in-house teams adapted to the rhythm of quarter-end filings and annual rollovers. The lesson stuck: Sustainable payroll systems are built not just for today’s rules, but for constant regulatory change. The Internet Turned Payroll Systems Into Connected Workflows With always-on connectivity, file uploads gave way to live data flows. Time clocks synced over networks, tax updates arrived automatically, and electronic direct deposit replaced paper checks. Employees could view stubs online, update their addresses, and change withholding information without needing to visit HR. Payroll began to integrate with accounting, time, and benefits in near real-time, reducing reconciliation tasks and shortening cycle times. Connectivity also ushered in new responsibilities: credential security, encryption, and audit logs became first-class requirements rather than nice-to-haves. Cloud-Native Payroll Systems and the Shift to Platforms Cloud applications reframed the job from running software to orchestrating a service. Vendors assumed responsibility for uptime, patches, security hardening, and tax table freshness. Finance and HR teams focused on policy and analysis, not servers and storage. The platform model invited integrations, including applicant tracking, scheduling, expense management, and general ledger systems, which began sharing data through APIs, eliminating the copy-paste loops that once plagued monthly closes. APIs and Integrations Systems now communicate with each other, so hours, rates, and cost centers are transferred automatically between tools. Mobile Self-Service Employees can correct their personal data, review their pay, and submit time from a phone, reducing administrative work. Real-Time Taxes and Filings Vendors continually push updates, ensuring that rules and forms stay current without requiring manual patch days. How AI and Analytics are Rewriting Payroll Systems Machine learning models can flag anomalies—an unexpected overtime spike, a duplicate payment, or a tax jurisdiction mismatch—before funds go out. Natural language interfaces turn complex queries into plain English answers: “Show me variance in labor cost by location this quarter.” Predictive analytics forecast accruals and cash requirements, reducing surprises on payday. Yet the most valuable outcomes are quiet ones: fewer errors, faster exceptions, and cleaner books. Even as AI expands, guardrails matter. Human review, explainable rules, and clear approvals ensure that decisions are traceable and compliant. Security, Privacy, and Trust Inside Modern Payroll Systems Payroll contains the crown jewels of employee data. Contemporary systems encrypt data at rest and in transit, enforce granular permissions, and record every meaningful action. Multi-factor authentication,

A team of engineers and independent contractors shake hands on a jobsite.
Employers’ Liability Insurance

Do Independent Contractors Need Liability Insurance for Commercial Work?

Do Independent Contractors Need Liability Insurance for Commercial Work? Home Blog Commercial jobs combine tight schedules, multiple trades, and public exposure, which means minor mishaps can quickly escalate into significant costs. A misplaced ladder can scratch curtain wall glass, a saw cut can nick a conduit, or a delivery can block a storefront, triggering a business interruption claim. Because contracts often shift responsibility to the party closest to the work, independent contractors are frequently the first target of a demand letter. Liability insurance steps in to defend, negotiate, and pay covered losses, so a disagreement doesn’t escalate into a lawsuit that drains cash flow. More importantly, carrying the proper coverage makes it easier to win bids, pass prequalification, and keep good standing with general contractors who expect every trade to bring professional risk management to the site. Independent Contractors Avoid Contract Killers With Coverage Commercial contracts are dense, and the language around risk transfer can make or break margins. When coverage is aligned to those clauses, conflicts stay contained, and work proceeds without legal detours. Additional Insured and Primary Noncontributory These requirements let an upstream party tap your policy first for your negligence, reducing finger-pointing and delays. Waiver of Subrogation Requirements A waiver prevents your insurer from pursuing an upstream party after paying a claim, thereby maintaining relationships intact on multi-trade projects. What Independent Contractors’ Policies Typically Cover in Plain Language A standard commercial general liability policy is built to respond when your operations cause third-party bodily injury or property damage. If a pedestrian trips on your cord, if overspray mists parked cars, or if a water line you tied in leaks and damages a tenant’s space, the policy provides defense and—if you’re found responsible—pays covered damages up to the limits. Products-completed operations extend protection after the job wraps, which matters when a defect shows up months later. The policy can also help with specific personal and advertising injury claims, such as alleged libel in an ad dispute. While the fine print matters, the intent is simple: take accusations of negligence off your personal balance sheet and hand the legal and financial heavy lifting to a carrier that does this every day. Where Independent Contractors are Still Exposed Despite Insurance No policy does everything, and assuming it does is how disputes get expensive. Knowing the edges lets you plan around them instead of being surprised mid-project. Professional Services Gaps Design advice, layout errors, and engineering guidance are typically excluded; consider separate professional liability insurance if you provide these services. Pollution and Asbestos Limits Many policies exclude or tightly limit environmental claims; the spec may require dedicated pollution coverage. How Much Independent Contractors Coverage Do You Really Need Limits should reflect your scope, project values, and the surrounding environment. A glazing sub working downtown near luxury retail needs higher limits than a rural fencing crew. Many owners require at least $ 1 million per occurrence and $ 2 million aggregate, plus an umbrella policy for larger exposures; tower work, hot work, cranes, or heavy public interface may push these limits higher. Consider a per-project aggregate endorsement to prevent a single large claim on Project A from eroding protection for Project B. If your work triggers long-tail risks—such as waterproofing, envelope ties, or structural connections—prioritize robust completed operations terms for the years following substantial completion. Adequate limits are not just about worst-case checks; they are also about leveraging negotiations and facilitating faster claim resolution when something goes wrong. What Proof Independent Contractors Need Before Mobilization Paperwork is the first safety barricade, and clean documents reduce back-and-forth that can stall a start date. Clean Certificates of Insurance Ensure that COIs reflect the current effective dates, correct entities, and project-specific language to avoid gate-check rejections. Endorsements Attached, Not Promised Attach copies of required endorsements—additional insured, primary and noncontributory, waiver of subrogation—so compliance isn’t based on a verbal assurance. What Independent Contractors Can Expect to Pay and How to Lower It Premiums vary by trade, payroll or receipts, claims history, location, and limits. Carriers price risk, not charm, so the path to better rates is disciplined controls and clean loss runs. Show underwriters your incident logs, toolbox talk cadence, hot-work permits, fall-protection plans, and subcontractor vetting process. Use written contracts with subs that mirror upstream requirements so you’re not absorbing their exposure. Bundle complementary lines—like inland marine for tools and equipment, commercial auto, and umbrella—to gain pricing efficiency and close common gaps. If you’re scaling, revisit limits and retentions at renewal; quietly outgrowing your program can lead to a capital problem with routine claims. When Claims Hit, Independent Contractors Need a Calm, Repeatable Plan The first hour sets the tone for the next six months. A steady response preserves evidence, protects people, and positions the claim for a swift outcome. Secure the Scene and Notify Get everyone safe, stop further damage, and notify the carrier and upstream parties quickly with facts, not guesses. Document Early and Neutral Photos, witness names, and a brief incident report can replace memory; keep language factual to avoid admissions or blame. Why Wrap-Ups and Project-Specific Programs Can Help Independent Contractors Large jobs often run on owner-controlled or contractor-controlled insurance programs. These wraps centralize liability coverage for enrolled trades, reducing carrier conflicts, standardizing limits, and streamlining claims across the site. Enrollment typically requires clean safety statistics and documented practices, but the payoff can be smoother administration and fewer disputes about whose policy applies. Understand how the wrap interacts with your own coverage—particularly completed operations and exclusions—so there are no gaps after demobilization. When a project offers project-specific professional or pollution policies, evaluate the terms; buying into the site’s structure can be cheaper and better aligned than piecing together separate endorsements. Independent Contractors and Personal Versus Commercial Protection Personal policies are not built for job-site risk. A homeowner’s or personal umbrella won’t stand in for commercial general liability when a tenant sues over water damage or a pedestrian is injured near your equipment. Commercial coverage is designed around contractual risk transfer,

A hand holding a pen goes to sign a certificate of liability insurance.
Employer’s Liability Insurance

How Liability Insurance Helps Prevent Costly Disputes on Job Sites

How Liability Insurance Helps Prevent Costly Disputes on Job Sites Home Blog On any active job site, dozens of moving parts converge: owners, general contractors, subcontractors, design teams, inspectors, suppliers, and the public. Where there’s motion, there’s risk, and where there’s risk, there’s potential for finger-pointing. Setting expectations early with clearly defined contracts and proof of coverage narrows the lanes for conflict. When every party can produce current certificates, show required endorsements, and demonstrate that coverage aligns with the scope and location, misunderstandings lose momentum. Instead of arguing about who is on the hook, teams can pivot to solving the problem, documenting it, and keeping the schedule intact. The quiet power of liability insurance lies not just in paying claims but in reducing ambiguity—so the job keeps moving and relationships stay intact. How Liability Insurance Guides Clear Risk Transfer on Mixed-Scope Projects Complex scopes invite complex disputes, especially when work overlaps between trades. A well-drafted contract that references the correct forms, endorsements, and limits provides project teams with a clear roadmap for assigning responsibility when something goes wrong. When that roadmap is clear, escalation to legal counsel is less likely, and minor issues stay small. Contractual Risk Transfer Explained Hold harmless and indemnity clauses define which party is responsible when third-party injury or property damage arises from their work. These clauses pair with coverage to keep liability aligned with the party best positioned to manage it. Additional Insured Endorsements Owners and general contractors often require additional insured status from subs so a claim can be handled within the at-fault party’s policy without sparking cross-suits. Primary And Noncontributory Wording This language helps ensure the responsible party’s policy responds first, avoiding disputes over which insurer pays before work resumes. Using Liability Insurance To Stabilize Emotions After an Incident When an incident occurs—whether a broken storefront window, a damaged utility line, or a slip-and-fall—people get stressed and projects get shaky. Immediate reporting, a calm explanation of how coverage responds, and a clear path to adjust and resolve the loss can de-escalate tension. Teams that know how to notify carriers, secure the scene, capture photographs, and collect witness statements provide adjusters with the necessary information to move quickly and efficiently. With that response, stakeholders see that the job is insured, the harm is addressed, and the project can continue to move forward. Disputes thrive in uncertainty; fast, informed action drains that uncertainty and maintains collaboration. Understanding What Liability Insurance Covers and Excludes No two policies are identical. Understanding the coverage perimeter helps reduce surprises when unexpected events occur. Just as important, it avoids promising solutions that the policy won’t provide, which is often what sparks disputes. Third Party Injury And Property Damage General coverage typically responds when your operations cause bodily injury to a third party or damage to someone else’s tangible property, on or off-site. Completed Operations Exposure Work can trigger claims after turnover. Completed operations coverage helps address post-completion losses associated with your completed work. Professional And Pollution Exclusions Design errors or pollution events often sit outside standard coverage. Knowing these edges steers teams toward separate professional or pollution policies if the project requires them. Liability Insurance as a Catalyst For Better Documentation Habits Good documentation is the cheapest dispute prevention tool available. Daily reports, photo logs, delivery receipts, and sign-offs establish a factual foundation that aligns with policy conditions and supports a seamless claim process. When teams treat incident logs, RFI tracking, and sign-in sheets as part of their standard craft—rather than a chore—adjusters can reconstruct what happened without guesswork. That reconstruction shortens the path from loss to resolution. Because policy obligations typically require timely notice and reasonable cooperation, disciplined recordkeeping doubles as both risk management and policy compliance. The end result is fewer arguments about “who did what” and a faster, fairer outcome for everyone. How Liability Insurance Shapes Safer Site Controls and Communication Coverage requirements often drive safer behaviors. Mandated barricades for public walkways, posted signage at active fronts, and documented toolbox talks are not just safety theater; they reduce the frequency and severity of incidents that lead to claims. Insurers notice—and reward—consistent controls with better terms over time. Visible Controls Reduce Confusion Clear fencing, signage, and traffic plans keep the public out of harm’s way and demonstrate diligence in the event of a claim. Training Converts Policy Into Practice Short, recurring safety huddles connect contract requirements to daily behaviors, making compliance second nature. Rapid Reporting Builds Trust Prompt notice to all parties demonstrates professionalism and prevents rumors from escalating into disputes. How Liability Insurance Supports Fair Change Orders Without Drama Change orders often become conflict flashpoints because scope, cost, and risk all change simultaneously. When pricing adjustments account for exposure—not just labor and material—everyone sees the whole picture. If a change introduces hot work, crane picks, or a public interface, the risk profile shifts. Documenting that shift and confirming that coverage remains appropriate prevents mismatches that fuel later disagreements. With risk acknowledged upfront, approvals come easier, and resentment doesn’t build in the background. Align Scope To Coverage When the scope changes, confirm that your coverage terms and endorsements still align with the new exposures before work proceeds. Price In Risk Not Just Labor Fair pricing includes the cost of controlling, transferring, or retaining new risks—not only the hands and hardware. Keep Waivers And Releases Clean Clear, contemporaneous releases for paid work close the door on old issues that can reappear as disputes later. Practical Ways Liability Insurance Streamlines Claims and Keeps Schedules The speed and clarity of claims handling often determine whether a project maintains momentum or stalls. Having a known adjuster contact, a predefined document set, and a simple escalation ladder gives teams confidence that issues will be handled professionally and quickly. Single Point Of Contact Designate one internal coordinator to gather facts, communicate with the carrier, and update the team so messages don’t cross. Early Reserve Setting When adjusters receive complete information early, they can set reserves realistically and move toward settlement without guesswork. Subrogation

Construction worker down after injury during site operations
Worker’s Compensation

What is Workers’ Compensation?

What is Workers’ Compensation? Home Blog When an employee gets injured on the job, it affects more than just their health—it impacts your operations, finances, and legal exposure. Even one incident can spiral into legal battles, medical costs, and staffing gaps without the proper protections. Workers’ compensation is the safety net shielding your employees and your company. Understanding how it works keeps your business secure and compliant from day one. What is Workers’ Compensation and Why Does It Exist Workers’ compensation is a state-regulated insurance system that pays for employee injuries or illnesses due to work-related duties. It provides coverage for medical expenses, lost wages, and disability support, while protecting employers from lawsuits. The system operates under a no-fault rule, meaning employees don’t need to prove employer negligence. This framework helps businesses resolve claims faster and avoid long-term legal disputes. Legal Coverage for Job-Related Injuries Workers’ compensation laws exist in every U.S. state and typically apply once a business hires its first employee. These laws require employers to carry insurance that pays benefits when a worker is injured or becomes ill due to work duties. In exchange, employees give up the right to sue the employer, creating a legal balance. State agencies regulate how much coverage is needed and how claims are handled. Businesses that fail to meet these legal obligations can face steep penalties. Knowing your state’s rules helps protect your operations and your team. Employers Fund the System, Not Employees Employers fully pay workers’ compensation through commercial insurance or self-insured programs approved by the state. Employees never pay into the system, and deductions from their paychecks are prohibited. Premiums are calculated based on your industry’s risk level, number of employees, and claims history. Higher-risk sectors like construction often pay more than lower-risk fields such as accounting. It pays to invest in safety improvements if you’re in a high-claim environment. A safer workplace helps lower future insurance costs. Why Workers’ Compensation Benefits Employers Workers’ compensation coverage isn’t just a legal formality—it protects your company from serious financial and legal risks. One injury without coverage can trigger out-of-pocket payments, lawsuits, and a damaged reputation. With the right plan, you manage risks more efficiently while demonstrating employee care. It helps maintain business continuity even during unexpected events. Avoiding Legal Penalties and Business Interruptions State labor boards monitor whether businesses carry required coverage. If uninsured, your company could be fined, sued, or even shut down, depending on state laws. These penalties often increase with each day you remain out of compliance. Legal costs from an uncovered injury could quickly exceed a year’s premiums. Staying covered allows you to focus on growth instead of crisis management. It also gives you peace of mind during audits or inspections. Preserving Profit and Controlling Liability Without coverage, you’re financially responsible for medical bills, wage replacement, and long-term disability costs. These expenses can stack quickly, especially for small businesses with limited cash flow. Workers’ comp limits employer liability while ensuring employees receive timely support. The plan also reduces the likelihood of lawsuits that can drain resources and harm your brand. Over time, proper coverage leads to a more stable financial outlook. Protecting your bottom line starts with anticipating risks. Supporting Human Resources and Workplace Culture Workers’ comp plays a quiet but vital role in your HR structure. It encourages retention by showing employees they’ll be supported if something goes wrong. This trust can boost morale and foster a culture of transparency. When paired with onboarding and safety training, it becomes part of your company’s identity. Human resources teams also benefit from a structured process for handling injuries and leave. The result is fewer surprises and smoother operations. What Workers’ Compensation Insurance Covers Workers’ compensation typically covers four categories: medical treatment, wage replacement, disability support, and death benefits. These protections apply to injuries or illnesses during or because of job duties. The exact details vary by state, but most plans follow similar guidelines. Knowing what’s included helps employers and employees avoid confusion during a claim. Immediate Medical Treatment and Ongoing Care Workers’ comp pays for their hospital visit, surgery, rehabilitation, and medications if an employee gets hurt. Coverage begins once the injury is reported and verified by the employer and provider. In some states, it also includes approved specialists or follow-up appointments. The injured worker should never be billed directly. All records must be documented and submitted to the insurer for processing. Timely care not only supports recovery; it reduces the risk of complications and extended downtime. Wage Replacement During Employee Recovery Employees who can’t work due to a valid workplace injury receive wage replacement through temporary disability payments. These payments typically cover around two-thirds of the employee’s regular income, up to a state-mandated cap. There may be a short waiting period before benefits begin. The duration of payments depends on medical evaluations and treatment plans. Employers must stay in communication to avoid delays in claims processing. Keeping injured staff financially supported speeds up return-to-work timelines. Disability Classifications and Long-Term Benefits If an injury results in permanent impairment, workers may qualify for long-term disability benefits. These can be partial or total, depending on the loss of function and the ability to return to work. Vocational rehab may also be included if an employee needs training for a new role. Death benefits are provided to surviving dependents if the incident is fatal. State agencies usually oversee how disability classifications are determined. Employers should understand these rules to manage expectations and plan staffing accordingly. What Workers’ Compensation Doesn’t Cover Not all injuries or claims qualify under workers’ compensation. The system only covers injuries directly related to the employee’s job duties. Claims related to personal behavior, misconduct, or activities outside of work are usually excluded. Understanding what’s not covered can help prevent costly disputes and false expectations. Injuries That Occur Outside Work Duties Workers’ compensation won’t cover injuries during personal errands, commutes, or activities unrelated to the job. For example, slipping at a grocery store during lunch isn’t eligible for

Human resources leader outlining talent development plan on whiteboard in business meeting
Human Resources

Why Human Resources is Critical for Business Growth

Why Human Resources is Critical for Business Growth Home Blog Business growth doesn’t happen through guesswork—it’s built with structure, purpose, and people. Most companies prioritize sales and operations but neglect the systems that support people management. That’s where human resources comes in, aligning daily functions with broader goals. When HR becomes a growth partner, momentum turns into long-term success. What Human Resources Actually Does in a Business Human resources manages the whole employee lifecycle, from hiring and onboarding to training, performance, and exit. It ensures that the right people join, grow, and contribute meaningfully to the organization. HR also handles compliance, payroll, benefits, and workplace policies to keep operations smooth and legally sound. Beyond administration, HR strategically shapes culture, supports leadership, and aligns talent with long-term business goals. How Human Resources Drives Business Success Behind every thriving company is a successful people strategy. Human Resources is more than support—the system powers growth from within. It touches every part of the business, from hiring to culture to compliance. Understanding what HR truly does sets the stage for why it matters in every growth phase. Aligns People Strategy With Business Goals Human Resources aligns talent management with business direction. It translates leadership objectives into clear staffing plans and culture initiatives. With HR driving execution, every hire, policy, and workflow supports measurable outcomes. That makes scaling possible without compromising quality or vision. Strategic HR Planning Supports Long-Term Growth Strategic human resources planning bridges the gap between company goals and team capabilities. It involves forecasting workforce needs based on growth timelines, service expansion, or market entry. HR evaluates existing talent against those projections and identifies where to build or hire. It creates a balance between speed and sustainability. Leaders can avoid talent shortages while staying lean. Growth happens when people are ready before the demand arrives. Workforce Scaling Matches Business Demands HR ensures companies grow their teams in sync with operations. It assesses role gaps, workload shifts, and budget limits as demand increases. Instead of hiring reactively, HR builds a phased expansion plan. That keeps onboarding manageable and the culture consistent. Fast growth without HR guidance leads to confusion and a poor fit. A scaled workforce only works when it’s structured for what comes next. Builds a Culture That Drives Business Results Culture drives how people think, act, and collaborate. HR defines the culture and ensures it matches the brand’s identity, goals, and standards. It becomes a system for decision-making and engagement at scale. When culture is intentional, teams stay aligned and productive during growth. Purpose-Led Culture Improves Collaboration Culture isn’t just perks—it’s clarity, consistency, and behavior. HR helps define values that guide teams across departments, locations, and levels. These values shape how employees handle challenges, give feedback, and solve problems. People take more ownership when their expectations are clear. A culture rooted in purpose reduces friction and misalignment. It keeps people moving in the same direction, no matter how fast the business grows. Internal Communication Builds Team Alignment Information gaps slow progress and increase errors. HR builds internal communication systems that keep everyone in sync. It includes regular updates, manager check-ins, and employee listening tools. When people feel informed, they stay engaged. Communication from HR reinforces trust and stability, especially during change. The result is faster decision-making and fewer misunderstandings. Cross-Team Connection Increases Agility Departments naturally drift apart as teams grow. HR helps maintain cross-functional coordination through shared tools, project alignment, and cultural touchpoints. These systems prevent silos and encourage knowledge transfer. Employees learn faster when exposed to different perspectives. This agility helps companies respond quickly to market changes. Collaboration becomes the norm, not the exception. Hiring Systems That Support Scalable Growth Recruitment shapes the future of any business. HR manages the process so hiring decisions support both short-term goals and long-term vision. It goes beyond filling positions to building teams that drive performance. New hires must align with culture, skill needs, and business priorities. Hiring Strategy Aligns with Business Vision HR develops hiring strategies based on company objectives. Instead of reactive hiring, it prioritizes roles that deliver impact. Job descriptions are tailored to future demands, not just current gaps. This approach improves retention and performance. The right hire saves time, reduces costs, and accelerates growth. Every position becomes a stepping stone toward the company’s next milestone. Employer Branding Attracts Quality Candidates Top candidates evaluate more than job titles—they look at the company story. HR builds and promotes an employer brand that reflects workplace culture, growth paths, and leadership values. That shapes how applicants view the organization before applying. A strong employer brand attracts applicants who align with company values. It lowers turnover and boosts performance. HR ensures this brand is consistent across platforms and touchpoints. Streamlined Hiring Processes Reduce Drop-Off Complicated hiring processes push good candidates away. HR simplifies steps with clear timelines, interview standards, and consistent follow-ups. It reduces delays, increases applicant engagement, and enhances the candidate experience. This professionalism reflects company values and attracts serious talent. It also improves collaboration between hiring managers and HR. Efficient hiring gives businesses a competitive edge in fast-moving markets. Retention Practices That Strengthen the Workforce Retention results from good leadership, fair processes, and meaningful work. HR creates an environment where people feel valued, supported, and challenged. It reduces turnover through planning, communication, and personal development. Businesses grow stronger when their teams grow with them. Effective Onboarding Builds Long-Term Loyalty A great first week shapes an employee’s long-term view. HR creates onboarding experiences that welcome, train, and empower new hires. Transparent orientation processes reduce anxiety and speed up productivity. Employees know who to turn to and what success looks like. That early clarity leads to stronger performance. It also increases the chance that great talent stays long-term. Skills Development Boosts Job Satisfaction HR makes learning part of the company culture. It identifies skills gaps and offers training, mentorship, or certifications that help people grow. When employees improve, they feel more confident and capable. It directly impacts quality, efficiency, and innovation. Regular development also builds

Word “insurance” on wood blocks.
Employer’s Liability Insurance

What Does General Liability Insurance Typically Cover?

What Does General Liability Insurance Typically Cover? Home Blog Running a business means carrying risk every day. Customers walk into your space. Vendors visit your job site. Clients trust you with their property and reputation. General liability insurance stands between you and financial ruin if anything goes wrong. It’s not just protection; it’s a business essential that keeps you in control when the unexpected hits. What General Liability Insurance Covers for Businesses General liability insurance protects businesses from third-party claims. These include customer injuries, property damage, and legal issues tied to your operations. It also covers legal defense costs and settlement payouts. This coverage is essential for businesses with physical locations, service calls, or public interaction. Bodily Injury to Customers and Visitors Bodily injury coverage applies when someone is physically hurt on your property. For example, if a customer trips over exposed wiring, this policy helps cover medical costs and potential legal fees. It also pays for damages if the injured person sues for negligence. Businesses in high-foot-traffic areas are especially vulnerable. Even a minor fall can trigger lawsuits that cost tens of thousands. This protection absorbs those costs, so your company doesn’t have to. Property Damage to Third Parties If your business damages someone else’s property, general liability steps in. Say your employee knocks over a client’s display screen during an on-site visit—this policy can cover replacement costs. It also helps resolve disputes quickly, avoiding lawsuits that slow down operations. Even small claims create friction with clients, which can harm long-term relationships. Property damage coverage helps maintain trust while protecting your cash flow. It’s especially crucial for service-based businesses and mobile operations. Personal and Advertising Injury Claims This part covers reputational damage caused by your marketing or public communications. If someone accuses your business of slander, libel, or false advertising, general liability insurance helps fund your defense. It also covers settlements or court awards related to those claims. These lawsuits can come from competitors, customers, or even former partners. Social media content, ad copy, and press releases can all trigger legal issues. This protection is key for businesses with any form of public messaging. Medical Payments for Minor Incidents Medical payments coverage applies even if your business isn’t legally at fault. It pays small, immediate medical bills for minor injuries on your premises. For example, if a visitor scrapes their knee or bumps their head, you can cover treatment without a lawsuit. It keeps interactions civil and avoids drawn-out disputes. Quick payment often prevents claims from escalating. It’s a practical way to resolve low-cost injuries without legal involvement. Legal Coverage Under General Liability Insurance General liability insurance doesn’t just handle payouts; it also covers legal defense. If your business is sued, this policy pays for attorneys, court fees, and related costs. That protection applies whether the claim has merit or not. Legal support keeps small businesses from getting buried under case expenses. Defense Costs Paid by the Insurer Legal fees add up fast, even for unfounded claims. General liability insurance assigns legal counsel to represent your business from the start. It also covers filing fees, expert witnesses, and administrative expenses tied to the lawsuit. These benefits apply regardless of the lawsuit’s outcome. Even dismissed cases can cost thousands without this protection. With a policy in place, your insurer absorbs those costs so you can stay focused on operations. Settlements and Court-Ordered Judgments When a case ends in a payout, your policy covers it up to your limits. That includes damages awarded by a judge and private settlements negotiated outside court. Without coverage, these amounts would come from your business revenue or reserves. Some claims result in six-figure judgments, especially if injury or property damage is involved. General liability ensures you’re not financially destroyed by one legal event. It acts as a buffer during your most vulnerable moments. What General Liability Insurance Doesn’t Include While general liability insurance covers many situations, it’s not universal. It excludes employee injuries, professional errors, and commercial auto accidents. Businesses often need additional policies to cover those risks. Understanding exclusions helps avoid dangerous gaps in your protection. Employee Injuries and Workers’ Compensation This policy does not cover injuries to your own staff. You’ll need a separate workers’ compensation policy if a worker gets hurt. That policy handles medical care, wage replacement, and disability coverage. General liability protects against claims from customers, vendors, or non-employees. Failing to separate these coverages can lead to denied claims. Always pair general liability with workers’ comp if you have a team on payroll. Professional Mistakes and E&O Insurance General liability does not cover advice, consulting, or service delivery mistakes. Those situations fall under errors and omissions (E&O) insurance. If your client sues because your advice caused financial harm, general liability will not help. That includes missed deadlines, incorrect data, or misrepresentation of services. For businesses offering expert or professional services, both policies are necessary. Combining E&O with general liability gives you complete protection. Vehicle Accidents and Commercial Auto Coverage Business-related car accidents are not part of this coverage. You need commercial auto insurance if your team uses company vehicles or drives for work. This policy covers damage to other vehicles, injuries, and legal claims tied to driving. Even if your employee uses their car for deliveries or site visits, personal insurance may not cover them—a general liability policy won’t apply in these situations. Add auto coverage to stay fully protected on the road. Coverage Limits in General Liability Policies Every general liability policy has financial boundaries. These include per-incident caps and annual payout limits. They also factor in deductibles and optional endorsements. Understanding limits helps you choose the right plan for your risk level. Per-Occurrence and Aggregate Limits The per-occurrence limit is the most your insurer will pay for a single claim. The aggregate limit is the most they’ll pay for all claims in a year. For example, a policy may offer $1 million per claim and $2 million annually. Once you reach that cap, you’re responsible for any

Lettered cubes spelling out "PAY" and "TAX" on top of banknotes and tax forms.
Payroll Services

How a Payroll Service Helps You Stay Compliant With Tax Laws

How a Payroll Service Helps You Stay Compliant With Tax Laws Home Blog Business owners face relentless pressure to comply with tax laws. Regulations shift frequently; even small payroll mistakes can trigger audits or fines. Staying current with deadlines, deductions, and filing requirements takes time most teams don’t have. Yet non-compliance can quietly drain resources and damage your credibility. Relying on a payroll service isn’t just convenient; it’s a strategic move to keep your business protected and aligned with the law. What a Payroll Service Does A payroll service isn’t just a tool for cutting paychecks. It’s a system that handles everything from taxes to time-tracking. The right service simplifies complex payroll processes for small shops and growing teams. Most importantly, it protects against tax errors that slip through the cracks. Handles Wage Calculations and Deductions Accurately Each employee’s paycheck includes regular wages, overtime, bonuses, and deductions. Calculating all these accurately is tedious without help. A payroll service runs those numbers precisely every time. It also ensures pre-tax and post-tax deductions are applied correctly. That includes health benefits, 401(k), and garnishments, if any. This accuracy reduces the risk of wage complaints or IRS corrections. Keeps Employee Classification Clear and Correct Mistaking a contractor for an employee, or vice versa, can trigger tax penalties. Payroll services categorize workers based on IRS standards. They maintain different tax forms for each type, like W-2 for employees and 1099 for contractors. They also handle different tax treatment rules without skipping any steps. This clarity protects your business from audits and legal issues. Maintains and Updates Payroll Records Recordkeeping is more than a backup; it’s a requirement. A good payroll service stores payment history, benefits, tax forms, and reports. These records stay organized and searchable when needed. If the IRS or state agency asks for documentation, it’s ready in minutes. That kind of readiness saves time and stress when under pressure. How Payroll Services Keep You Tax-Compliant Payroll tax compliance isn’t a one-time task but an ongoing commitment. Tax laws change across federal, state, and even city lines. Payroll services monitor these shifts constantly, adjusting your systems automatically. That’s how they help keep your business from falling behind. Files Local, State, and Federal Taxes On Time Each jurisdiction has its own deadlines and reporting formats. A payroll service tracks every calendar and submits payments accordingly. Whether it’s income tax, unemployment insurance, or Social Security contributions, timing matters. Delays trigger penalties, interest charges, and damaged reputations. Automation through a payroll service prevents late filings and keeps your books clean. Applies the Right Tax Rates Without Guesswork Tax rates vary by location, industry, and worker status. Manually applying tax rates increases the risk of errors that lead to penalties. Payroll services use real-time databases to pull updated tax rates instantly. That ensures accurate withholding for every check issued. There’s no need to double-check because the calculations are correct from the start. Tracks and Manages Tax Form Deadlines W-2s, 1099s, and quarterly filings can quickly overwhelm your workflow. Payroll services track due dates and generate forms in the correct formats. They also send alerts if any information is missing. This way, you never scramble at the last minute. Your tax forms arrive on time, reducing audit risk. Adjusts for Seasonal or Industry-Specific Regulations Some industries face unique tax situations, like tip reporting or union contributions. Payroll services cater to these specifics by configuring the software for your industry. They know when to apply niche exemptions or special wage calculations. This precision prevents compliance issues tied to your line of work. Avoiding Costly Errors With a Payroll Service Tax errors can shut down a business faster than poor sales. Fines multiply, and correcting mistakes drains resources. Payroll services are built to spot issues before they land you in trouble. Their layered approach protects both your team and your bottom line. Prevents Penalties From Late or Incorrect Filings A single late payroll filing can trigger costly penalties and compliance issues. A payroll service reduces that risk through built-in checks and automatic submissions. It alerts you before a filing is missed and verifies figures before submission. These extra steps prevent slip-ups that create a domino effect. You stay in the IRS’s good graces and avoid stress. Flags Misclassification and Wage Violations Some businesses unknowingly underpay workers or apply the wrong wage rules. That often happens with misapplied overtime rules or incorrect exemption classifications. Payroll services monitor your wage patterns and flag potential violations. They help adjust records before an inspector does. Avoiding wage theft accusations is a win for compliance and employee trust. Alerts You to Tax Law Changes That Affect Payroll Tax codes change frequently, often without broad notice or warning. These changes can impact how you file, what you withhold, or which credits you can use. Payroll services stay current by updating their systems as rules shift. You’ll receive notifications and support when laws impact your setup, keeping you ahead of compliance risk. How Payroll Services Make Audit Preparation Easier During an audit, accurate records carry more weight than good intentions. Missing documents can cause penalties even if you did nothing wrong. Payroll services organize your financials to match what auditors want to see. That keeps inspections short and smooth. Stores All Tax Records in One Central Place Scattered records create chaos during audits. A payroll service keeps tax forms, reports, and receipts in one digital hub. You can pull up anything by employee, date, or filing period. This centralization streamlines prep and reduces errors. Auditors value fast access and consistency. Generates Reports That Match IRS and DOL Requirements Different agencies want different report formats. Payroll services generate reports tailored to each department’s guidelines. It avoids back-and-forths and rejected documentation. It also speeds up the audit process so your team can return to work. Compliance isn’t just about paying taxes but presenting proof correctly. Helps You Prove Compliance During Random Checks Sometimes agencies perform random or complaint-driven reviews. These aren’t always triggered by wrongdoing. Payroll services prepare you

A business owner holding a liability insurance certificate and a pen reviews the documents before signing.
Employer’s Liability Insurance

What Does Liability Insurance Cover?

What Does Liability Insurance Cover? Home Blog Business moves fast, but risk moves faster. One unexpected accident, on-site or off, can result in lawsuits, medical bills, or damaged relationships. Liability insurance isn’t optional for any company with workers, contractors, or third-party exposure; it’s foundational. It protects you when someone gets hurt, property is damaged, or legal action follows. Employers should know what liability insurance covers, including those who place workers in external environments. Why Understanding Liability Insurance Lowers Risk Legal claims don’t wait for ideal timing. Whether you’re onboarding employees, expanding to new locations, or partnering with clients, liability exposure grows. Insurance allows you to move forward without fear that one accident or claim will derail your progress. It’s not just coverage but a sign of operational discipline and long-term thinking. What Does Liability Insurance Cover in Business? Liability insurance protects companies from legal and financial responsibility when they cause harm to others. That harm could be physical injury, property damage, reputational loss, or failure to act with due care. Policies differ based on how and where you operate, but the goal is consistent: to shield your business from the fallout of claims. Employers who hire directly or place staff at third-party locations should pay close attention to how coverage applies. What Employer’s Liability Insurance Covers Employer’s liability insurance steps in when a worker claims injury or illness and alleges that the employer’s negligence was to blame. It supports legal defense, pays settlements or court awards, and complements workers’ compensation coverage. This coverage is especially relevant for companies that hire workers for physical roles or assign them to external workplaces. Whether you run a factory or provide staffing solutions, this policy helps you meet your responsibilities as an employer. Coverage for Negligence-Linked Worker Injuries Your business could be held responsible if a worker is injured due to faulty equipment, lack of training, or unsafe conditions. Employers’ liability insurance helps cover legal fees and financial damages when workers’ compensation doesn’t fully handle those injuries. This coverage is vital for employers who oversee hazardous tasks or fast-paced environments. If you place staff into roles outside your workplace, you may still be liable depending on your contract terms. Having insurance to address that risk is an innovative business. Legal Protection for Occupational Illness Claims Some workplace exposures don’t result in immediate injury. Long-term effects like respiratory conditions from fumes or joint damage from repetitive tasks can surface months or years later. If your employee alleges that the illness is job-related and sues for damages, the employer’s liability insurance responds. That is crucial for industries with physically demanding roles or less controlled environments. For employers managing on-site teams or deploying workers to client locations, this risk grows with scale. Indirect Claims Through Third-Party Lawsuits Sometimes your employee sues a third party, such as a property owner or equipment vendor. You could face a secondary claim if that third party sues your business for contributory negligence. Employers’ liability insurance helps you defend against these complex cases. Indirect claims are more common than most companies realize, primarily when multiple businesses interact in one workplace. This coverage gives you legal and financial support when disputes escalate. General Liability Insurance for Businesses General liability insurance protects your company from claims by third parties, such as customers, visitors, vendors, or the public. It covers injuries, property damage, and specific legal actions tied to your operations. This type of insurance is foundational for any employer interacting with clients or the public. It also helps if your staff causes damage while working at another location, whether it’s your job site or someone else’s. Third-Party Injury on Business Premises If a delivery driver slips on your property or a vendor is injured while inspecting your equipment, your company may be liable. General liability insurance covers their medical costs, legal expenses, and possible compensation. These incidents are unpredictable but expensive to resolve. Whether you run a retail storefront, a production facility, or a professional office, third-party injuries are a constant exposure. This insurance keeps one accident from turning into a financial crisis. Damage to Others During Business Operations General liability can cover the repair or replacement costs if your employee accidentally breaks equipment at a client’s location or damages property while providing services. It is vital for businesses whose operations involve movement between sites. Coverage also applies to subcontractors or temporary staff you oversee. It supports smooth client relationships and reduces friction when mistakes happen. Protection Against Reputational Claims Sometimes harm isn’t physical; it can be reputational. General liability insurance can respond if your business is accused of slander, libel, or using copyrighted materials improperly. It includes advertising materials, social media content, or verbal statements. These risks are real for companies that publish content, market services, or communicate externally. Having this protection avoids sudden legal fees and PR fallout. Liability Insurance Coverage for Business-Owned Vehicles Commercial auto liability insurance is essential if your business owns or operates vehicles. It protects you when a company-owned vehicle causes damage or injury. That applies to deliveries, field service, site visits, or transportation work. Employers who assign vehicles to staff, especially for client-facing roles, should consider this non-negotiable. Bodily Injury from Vehicle Accidents Your business may face a lawsuit if your driver causes an accident that injures someone. Auto liability insurance covers the injured party’s medical bills, lost wages, and potential legal action. These costs often climb well into six figures. Without coverage, a single accident could seriously damage your finances. Even minor fender benders can escalate if legal claims follow. Damage to Other Vehicles or Property Crashing into another car isn’t the only concern. You’re responsible if your vehicle damages a fence, building, or city property. Commercial auto liability pays for those repairs. This protection keeps operations moving without added liability for companies that operate a fleet or regularly travel to job sites. It’s one less thing to worry about in an already complex workday. Legal Defense from Auto-Related Lawsuits Legal costs after an accident

Scroll to Top